Catch up on the essentials
- Sandisk and Intel are both scheduled to report quarterly results on October 29, according to TipRanks.
- Sandisk was reported to trade at about 6.4 times expected earnings for the year.
- The report noted that Mizuho reiterated an Outperform rating on Sandisk and expected flash-memory pricing outside China to remain stable because capacity was expected to change little.
Selected from this article · 2026-10-23
Read on for the full pictureSandisk’s October 29 earnings report is the next focus
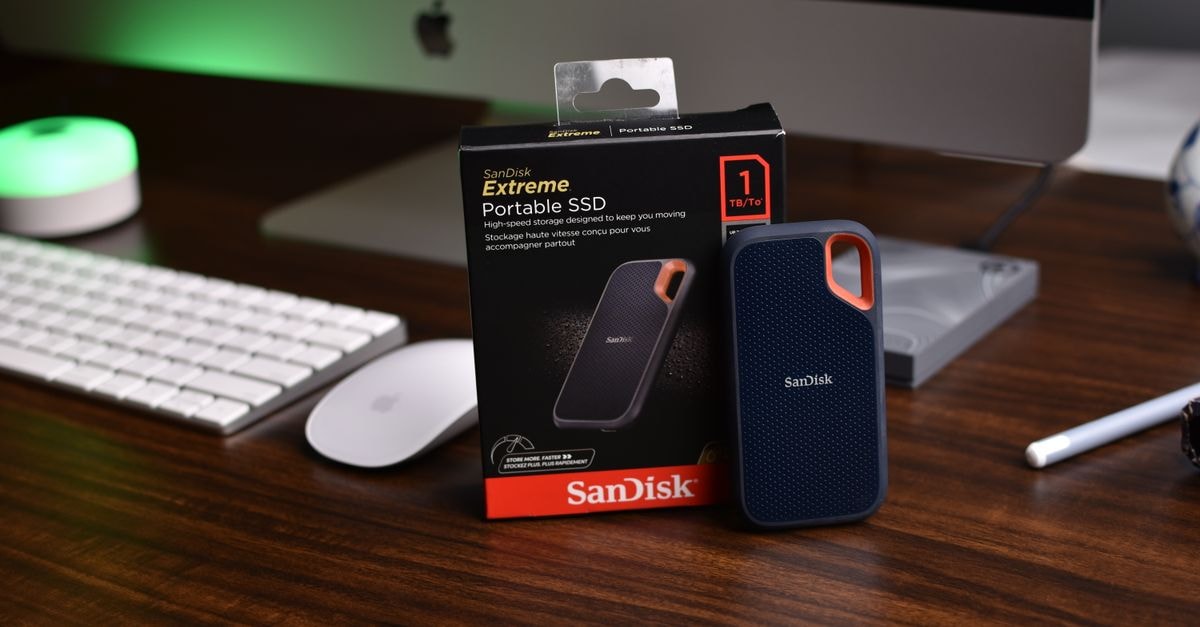
Sandisk and Intel are both scheduled to report quarterly results on October 29, according to TipRanks. The Sandisk preview comes as the company’s shares have retreated in recent weeks amid broader concerns about the funding and returns of the artificial-intelligence buildout. One investor, Julia Ostian of TipRanks, rated Sandisk a Buy ahead of the anticipated report, while warning that the stock would probably remain volatile.
The reporting schedule is prospective; the supplied information does not establish that results have been released. The investor’s Buy view is an attributed opinion rather than company guidance or a reported consensus target.
Investor focuses on growth, margins and guidance
TipRanks reported that Sandisk’s last-quarter revenue rose 372% from a year earlier, gross margin reached about 85%, and earnings per share exceeded management’s forecast. Management forecast gross margin of 83% to 85% for the current quarter, with the midpoint slightly below the 84.6% previously reported.
The preview identifies the outlook as the main issue for the October 29 report. Ostian said she wants to see price growth that keeps pace with the wider market, although she does not expect Sandisk to match Micron’s recent NAND results because of limits in Sandisk’s long-term contracts and slower sales-volume growth.
Long-term contracts support visibility but limit upside
Eight customers have committed to at least $93.9 billion of purchases at guaranteed minimum prices, according to the TipRanks preview. Those agreements are expected to cover more than half of Sandisk’s output this fiscal year, making earnings more predictable, but contract volume is expected to generate margins of around 80%, limiting how much profitability can rise from those sales.
Sandisk was reported to trade at about 6.4 times expected earnings for the year. The current-quarter forecast was described as more than 60% of the prior year’s total earnings; if earnings remained at that level for the rest of the year, the investor estimated the stock would trade below eight times earnings. These are investor calculations or estimates, not reported results.
Memory-sector selling has intensified
Separately, Sandisk shares fell 8% on October 22, while Western Digital fell 7% and Micron fell 6%, according to 24/7 Wall St. The Roundhill Memory ETF fell 7%, compared with a 2.77% decline in the Invesco QQQ Trust, indicating that the reported selling was concentrated in memory and storage stocks.
The selloff was attributed to concerns about Chinese competition, including possible additional supply from companies such as CXMT, and uncertainty about AI spending. The report noted that Mizuho reiterated an Outperform rating on Sandisk and expected flash-memory pricing outside China to remain stable because capacity was expected to change little. That view did not prevent the broader sector selling, and the sources do not establish a causal relationship between the stock declines and any individual analyst rating.
What to watch on October 29
The next verifiable milestone is Sandisk’s scheduled quarterly report on October 29. The key reported points for investors are the company’s forward outlook, price trends, contract economics and whether evidence of business performance supports the view that the recent decline reflects sentiment rather than a deterioration in operations. No actual revenue, earnings or margin results for the upcoming quarter are available in the supplied material.
Share this article