Catch up on the essentials
- ONGC’s stronger Q2 FY27 profit was driven primarily by higher oil and gas realizations rather than expanding production.
- Gas pricing supported revenue, but production remained below the prior-year level.
- The engagement is an operating support arrangement aimed at arresting natural declines in mature fields and accelerating production; the reviewed reporting does not separately quantify its expected production gain.
Selected from this article · 2026-11-05
Read on for the full picturePrice realizations powered ONGC’s earnings surge
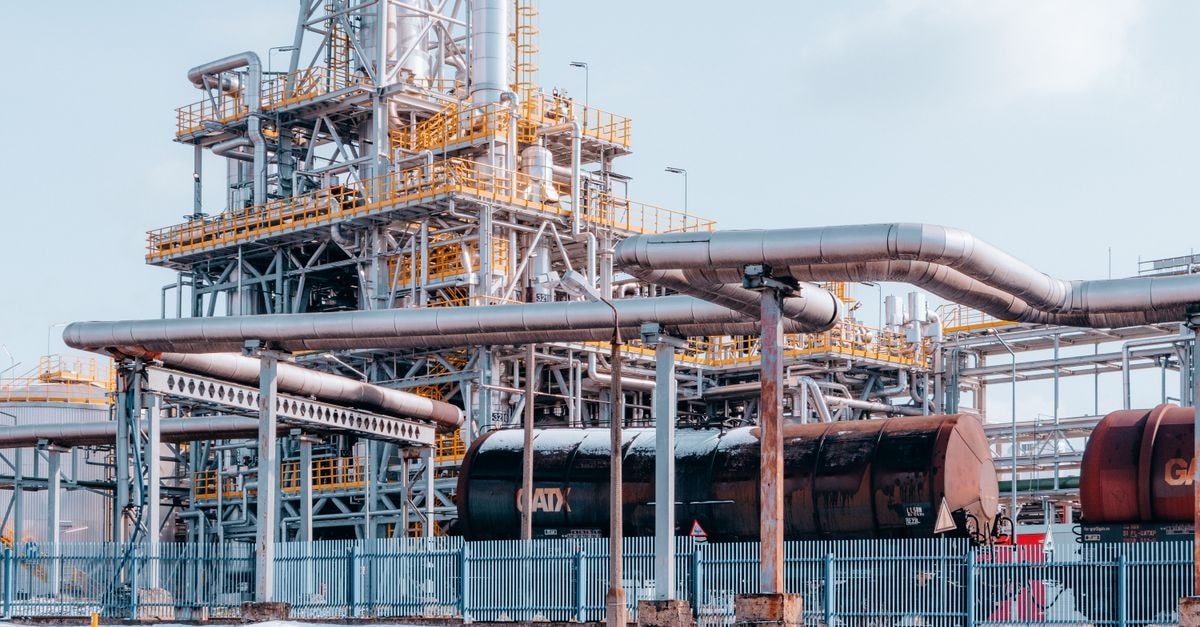
ONGC’s stronger Q2 FY27 profit was driven primarily by higher oil and gas realizations rather than expanding production. Standalone net profit rose 57.3% year on year to ₹15,488.64 crore in the July-September quarter, while revenue from operations increased 32.8% to ₹43,875.15 crore. Reuters reported that standalone profit, which excludes joint ventures and overseas assets, rose to ₹154.89 billion from ₹98.48 billion.
The transmission mechanism was pricing. Nominated crude-oil realizations increased to $92.33 a barrel from $67.34 a year earlier, while the reported net profit margin expanded to 35.3% from 29.8%. Benchmark Brent crude averaged nearly 40% higher year on year during the quarter. These figures show how the commodity-price environment lifted upstream earnings, but they do not establish a corresponding increase in ONGC’s physical output.
The results also had a sequential counterpoint: standalone profit fell to ₹15,488.64 crore from ₹17,033.81 crore in the preceding April-June quarter, and revenue declined to ₹43,875.15 crore from ₹46,460.45 crore. Thus, the year-on-year headline masks weaker quarterly momentum even as realizations remained supportive.
Gas earnings improved without matching output growth
Gas pricing supported revenue, but production remained below the prior-year level. The price of nomination gas rose marginally to $7 per MMBtu, and new-well gas prices increased to $10.24 per MMBtu from $8.36 per MMBtu. Revenue from new-well gas reached ₹7,050 crore during the first half and represented more than 34% of ONGC’s nomination-gas revenue.
Standalone natural-gas production was 4.839 billion cubic meters in Q2 FY27, down from 4.918 billion cubic meters a year earlier. ONGC attributed the year-on-year moderation to reservoir-behavior complexities at the KG-98/2 asset, monsoon-related operational challenges, delays in the PRP-8 and PRP-9 pipeline-replacement projects, and lower customer offtake following disruptions at certain major consumer facilities.
That combination matters for the natural-gas industry analysis: the quarter demonstrated pricing power and demand at ONGC’s realized gas level, but it did not demonstrate unrestricted physical throughput. Consumer-facility disruptions are distinct from proved reserves or an addressable procurement opportunity, and the available reporting does not quantify how much gas was constrained by those outages.
Oil production limits the volume contribution
ONGC’s production was broadly stable sequentially but declined year on year. Standalone crude-oil production was 4.437 million metric tonnes in Q2 FY27, compared with 4.630 million metric tonnes in Q2 FY26, while first-half crude output was 8.890 million metric tonnes.
The earnings comparison therefore points to two different mechanisms operating simultaneously: higher realizations increased revenue and profit, while lower physical production constrained volume growth. Total expenses rose 19.5% to ₹285.70 billion, showing that stronger revenue did not translate into unchanged costs. The result supports the inference that Q2 profitability was more commodity-price-sensitive than output-led, although the reporting does not provide a full bridge of the year-on-year profit change.
Capital projects expand the potential supply response
ONGC awarded two offshore development projects in the Western Offshore region with combined investment of approximately ₹11,800 crore. The company reported that they are intended to unlock an estimated 22 MMTOE of hydrocarbon potential. This is a disclosed project award and an indicator of prospective production capacity, not evidence that the full volume is already flowing or that a particular equipment supplier has been selected.
The company also expanded bp’s engagement as technical service provider for the entire Western Offshore under TSP-1 and TSP-2. A bp team was mobilised for TSP-2 in August 2026, covering the Western Offshore except the Mumbai High field. The engagement is an operating support arrangement aimed at arresting natural declines in mature fields and accelerating production; the reviewed reporting does not separately quantify its expected production gain.
Two hydrocarbon discoveries were notified during Q2 FY27: the onland prospect discovery Amraghat-1 and the new-pool discovery Vadatal-48. Together with the offshore awards, they broaden ONGC’s prospective resource base, but discovery and project-potential figures should not be read as realized production.
Strong cash returns accompany operational constraints
ONGC’s board approved a first interim dividend of ₹8 per equity share, equal to 160% and representing a total payout of approximately ₹10,064 crore. The record date for shareholder eligibility was set for November 12, 2026. The board also approved an inter-corporate loan of up to ₹10,000 crore for ONGC Videsh Limited, valid for five years, with the outstanding amount capped at ₹10,000 crore at any point.
The dividend is an approved cash distribution, not a purchase commitment or evidence of new procurement. Nor does the loan constitute realized spending: it establishes a financing facility with an agreed ceiling, not a completed transfer of the full amount.
The next operational test is whether ONGC can convert the higher gas and oil prices into sustained production and revenue. Observable indicators include quarterly gas and crude volumes, the effect of customer offtake recovery and pipeline-replacement work, and production progress on the two awarded Western Offshore projects. The available reporting does not establish a delivery timetable for the estimated 22 MMTOE potential or a quantified production target for bp’s expanded technical-services role.
Industry and product implications
Industry / product | Disclosed fact | Demand interpretation | Verification signal | Main risk |
|---|---|---|---|---|
Western Offshore development projects | ONGC awarded two offshore development projects with combined investment of approximately ₹11,800 crore, intended to unlock an estimated 22 MMTOE of hydrocarbon potential. [4] | Disclosed fact; awarded. Offshore development projects could increase future hydrocarbon production; the reported potential is not realized output. | Confirm subsequent project execution, production progress, and actual hydrocarbon output. | The award is confirmed, but the timing and realization of the estimated potential remain unknown. |
bp technical services for Western Offshore | ONGC expanded bp's engagement as Technical Service Provider for the entire Western Offshore under TSP-1 and TSP-2, and bp mobilised its team for TSP-2 in August 2026. [4] | Disclosed fact; operating. Technical support is intended to arrest natural declines in mature fields and accelerate production. | Check subsequent production performance and any disclosed production contribution from the expanded engagement. | The engagement is disclosed, but a quantified production benefit is not provided. |
Amraghat-1 and Vadatal-48 hydrocarbon discoveries | ONGC notified two hydrocarbon discoveries during Q2 FY27: the onland prospect discovery Amraghat-1 and the new-pool discovery Vadatal-48. [6] | Research watchlist; unknown. The discoveries may broaden ONGC's prospective resource base, subject to appraisal and development. | Confirm appraisal results, development decisions, and subsequent production. | A discovery is not equivalent to proved reserves, an award, or realized production. |
Share this article