The investment case — and what could go wrong
- Net income was $61.9 million versus $75.9 million a year earlier, and diluted earnings per share were $0.60 versus $0.71.
- Q2 2026 net sales of $418.0 million produced $158.3 million of gross profit, a 37.9% gross margin, and $86.2 million of operating income.
- Distribution-channel concentration is the structural vulnerability: the company sells to a relatively narrow tier of distributors and home centers, and 10-K risk factors disclose the dependence on a small number of large customers without naming them.
Selected from this article · 2026-10-15
Read on for the full pictureThe Quarter in Context
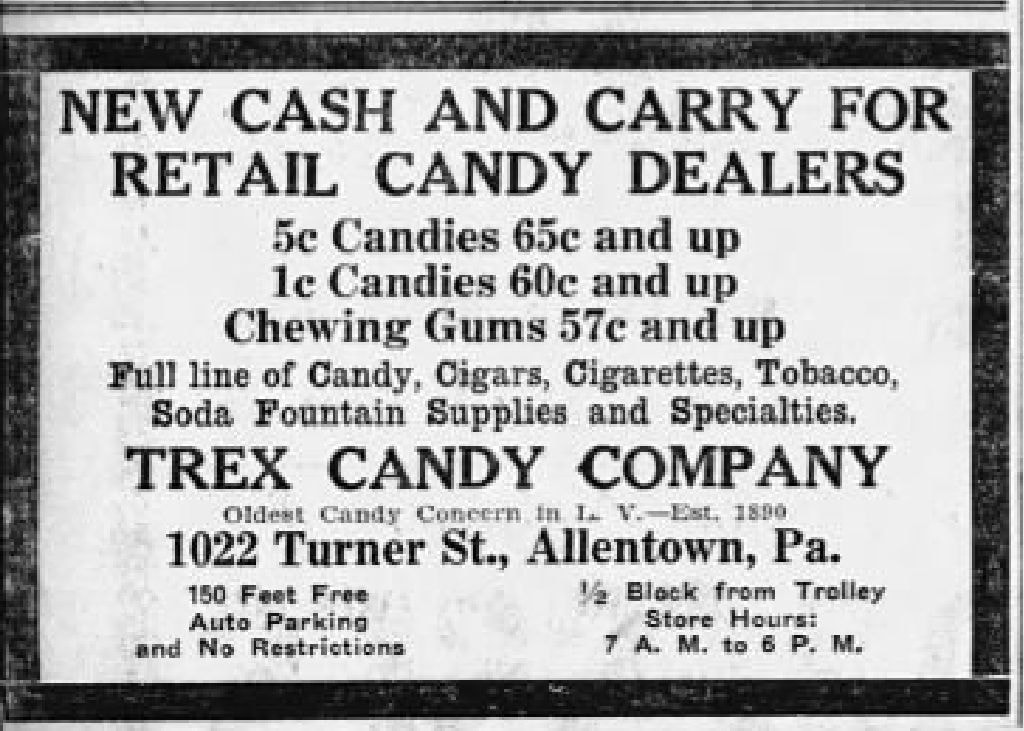
Trex reported $418.0 million of net sales for the three months ended June 30, 2026, compared with $387.8 million in the prior-year quarter. Net income was $61.9 million versus $75.9 million a year earlier, and diluted earnings per share were $0.60 versus $0.71. Operating cash flow for the quarter, derived by subtracting the cumulative first-quarter outflow from the cumulative six-month figure, was $214.2 million (author calculation from SEC-Q), while the company also recorded a $4.7 million asset write-down at its Virginia facilities. For the six-month period, gross margin compressed to 39.1% from 40.7% as input costs, depreciation and unfavorable mix outweighed productivity gains.
The more revealing comparison is the year-over-year movement of the second-quarter income statement: a 7.8% revenue gain alongside a 15.8% decline in operating income. SG&A rose to $67.5 million from $55.7 million, and other expenses of $4.7 million replaced a prior-year zero, together explaining roughly two-thirds of the operating-income gap. This is a franchise showing top-line momentum but a cost structure that did not fully leverage the incremental volume. The dated market capitalization was $4.52 billion on October 15, 2026, against shares outstanding of 101,865,190 as of June 30, 2026, and the market price implies continued operating recovery that the latest quarterly evidence only partially supports.
Business Model and Profit Engine
Trex operates as a single-segment manufacturer of composite decking, railing, fencing, cladding and outdoor lighting products, sold primarily to wholesale distributors, lumber dealers and two national home-center retailers that, in turn, supply the residential repair, remodel and new-construction markets. Customers pay for outdoor living products that compete against wood on maintenance, longevity and aesthetics; revenues are recognized at the point of shipment under contracts of less than one year. Q2 2026 net sales of $418.0 million produced $158.3 million of gross profit, a 37.9% gross margin, and $86.2 million of operating income.
The principal revenue engine is a tiered distribution channel in which Trex is a price-setting branded supplier; the company does not disclose customer-level economics, but the 10-K identifies more than 6,700 retail locations carrying Trex products and notes that the largest channel partner concentration sits with two national home-center merchandisers. Within the cost structure, cost of sales absorbed 62.1% of revenue in Q2 2026, indicating that raw materials (reclaimed wood fiber and recycled polyethylene), depreciation, and manufacturing throughput dominate the unit economics. SG&A at 16.1% of revenue shows fixed brand-building, sales force and dealer-support costs that do not scale instantly with volume. The gross-margin compression in the half, from 40.7% to 39.1%, demonstrates that incremental input and material costs are not yet fully recovered through pricing.
Capital intensity is meaningful: $52.7 million of capex was deployed in the first half of 2026, including $20.0 million for the Arkansas facility, $6.5 million of cost-reduction projects, $4.5 million for ERP and platforms, and $26.3 million for capacity expansion. Working capital was a cash use in the half as accounts receivable expanded by $214.5 million on higher seasonal volume, only partly offset by a $49.0 million inventory drawdown. Stock-based compensation of $5.5 million for the half is modest relative to net income. The profit engine is therefore a high-gross-margin, fixed-cost manufacturing platform whose working-capital seasonality can mask underlying operating quality in any single quarter; we label the absence of true unit-economics or contribution-margin disclosure as a data gap.
Earnings Quality and Cash Conversion
Where the issuer reports cash flow and capital expenditure cumulatively, the standalone-quarter cash-flow figures are derived by subtracting the preceding cumulative filing. They are calculations from SEC facts rather than separately reported quarterly line items. Reported net income of $61.9 million in Q2 2026 included the $4.7 million Virginia asset write-down that is a real economic cost, not a one-time accounting artifact. Operating cash flow of $214.2 million for the quarter (derived by subtracting cumulative Q1 from cumulative six-month operating cash flow, both reported in SEC-Q) materially exceeded net income, driven by working-capital movements; accounts receivable absorbed cash while accounts payable and accruals added cash. The headline operating-cash-flow-to-net-income ratio is therefore flattered by timing, not by capital-light economics, and we caution against reading it as durable quality.
On a trailing-twelve-month basis, operating cash flow was $358.1 million and capital expenditure was $150.1 million, implying $208.1 million of accounting free-cash-flow proxy (operating cash flow less total capex, with the limitation that the filings do not separate maintenance from growth capex). Six-month capex of $57.3 million was also well below the prior-year $126.3 million, so the comparison is biased by timing of Arkansas-facility spend. Depreciation and amortization of $37.7 million for the half is rising as new capacity enters the depreciable base. Share repurchases of $153.6 million during the half, funded partly with revolver borrowings, reduced diluted shares to 102.4 million from 107.3 million a year earlier. The earnings-quality picture is therefore mixed: a real write-down, working-capital-driven cash flow, and a shrinking share count supported by leverage rather than purely retained earnings.
Business Quality, Moat, and Industry Position
On the available evidence, the company is best described as an important participant, not a demonstrated core supply-chain bottleneck. This classification describes strategic position only; it is not independent proof of a moat or valuation upside. Trex markets itself as the world's largest manufacturer of composite decking and railing, with a brand that the 10-K describes as holding the highest unaided and aided recognition in its category. The economic moat, as far as the filings disclose, rests on brand, proprietary recycled-material manufacturing know-how, code listings on decking and railing, and a two-tier distribution network that includes two national home-center merchandisers. Distribution-channel concentration is the structural vulnerability: the company sells to a relatively narrow tier of distributors and home centers, and 10-K risk factors disclose the dependence on a small number of large customers without naming them. The capital intensity of the Arkansas facility and the durable-product warranty (50 years on Transcend decking for residential use post-2023) indicate that the competitive moat is built over multi-year horizons rather than quarter-to-quarter.
What the available evidence does not contain is any externally verifiable scuttlebutt on dealer satisfaction, contractor pull-through, or competitor share data; that gap is acknowledged here rather than filled in. The 10-K narrative on growth strategy emphasizes material conversion from wood, system attachment in railing, digital demand conversion, distribution expansion, and value-accretive acquisitions. A $4.7 million asset write-down at the Virginia facility during Q2 2026, disclosed as a reduction of carrying value to estimated fair value, suggests some existing capacity is no longer producing at expected returns. We treat these factors as the observable moat and industry-position evidence; everything else would be author inference.
Management and Capital Allocation
Management's most visible capital-allocation decision in the half was a $153.6 million share repurchase, executed in part through a $100 million accelerated stock repurchase agreement and supplemented by an additional 10 million shares of authorization in April 2026 and a $150.0 million authorization in July 2026. Cash dividends were not declared in the period; the metrics packet shows no dividends-paid line item. The company drew $253.0 million on its revolving credit facility at quarter-end, up from $133.5 million at year-end 2025, providing capacity for both the repurchase and the Arkansas investment. Stock-based compensation of $5.5 million in the half is small relative to net income, suggesting that dilution is not a primary concern at current compensation scale.
The capital allocation trade-off is therefore clear in the filings: growth capex on a new manufacturing platform plus aggressive buybacks funded partly with revolver borrowings. The 10-K describes capital-allocation priorities for 2026 as internal growth, manufacturing cost reductions, equipment and systems upgrades, value-accretive acquisitions, and return of capital to shareholders. Management has also disclosed 2026 capital expenditure guidance of $100 million to $120 million. The observable conduct is consistent with the priorities statement, though the pace of repurchase relative to leverage is a question that only the full credit-agreement package can resolve, and only the covenant compliance statement is in the available filings.
Valuation and What the Market Already Expects
The dated market capitalization was $4.52 billion at $44.37 per share on October 15, 2026, against 101,865,190 shares outstanding at June 30, 2026. The available cash-flow package shows $208.1 million of trailing operating cash flow less total capex as an accounting free-cash-flow proxy, against a share count that is being reduced month by month. The 10-K notes that Trex has $450 million of industrial revenue bonds associated with the Little Rock facility, but the company is both bondholder and borrower, with the asset and liability reported net, so the funded debt visible on the balance sheet is the $253.0 million revolver balance plus other accrued items.
Because the dated market capitalization materially exceeds the base-scenario equity value derived from the available free-cash-flow inputs, the price already requires operating normalization beyond the trailing twelve months, including margin recovery toward the 40.7% gross margin achieved a year ago and continued share reduction at the buyback pace observed in the half. The same-date net cash position could not be computed from the available SEC data, so the bridge excludes any balance-sheet adjustment. We discuss the qualitative implication only: the market is paying for an outcome rather than for the run-rate cash flow in the filings, and any thesis must rest on the likelihood that run-rate cash flow recovers and that the repurchase program keeps shrinking the share count.
Ten-Year Cash Flow to Fair Market Value
The starting free cash flow is the normalized SEC cash-flow proxy, while every growth rate, discount rate and terminal rate below is an explicit editorial assumption rather than company guidance. Each annual cash flow is forecast and discounted separately; terminal value is year-ten free cash flow multiplied by one plus terminal growth, divided by discount rate minus terminal growth, and then discounted back ten years. Fair market capitalization equals that explicit ten-year present value plus discounted terminal value and a same-date balance-sheet adjustment when available. If current cash and debt facts do not share one report date, the table shows the adjustment as unavailable and conservatively applies zero. The share count is derived from the dated market capitalization and share price so US shares and foreign ADRs use a consistent traded-security denominator.
Year | Bear FCF | Base FCF | Bull FCF |
|---|---|---|---|
1 | $204M | $216M | $229M |
2 | $200M | $225M | $252M |
3 | $196M | $234M | $277M |
4 | $192M | $243M | $305M |
5 | $188M | $253M | $335M |
6 | $191M | $261M | $352M |
7 | $193M | $269M | $369M |
8 | $196M | $277M | $388M |
9 | $198M | $285M | $407M |
10 | $201M | $293M | $428M |
Scenario | Growth years 1–5 / 6–10 | Discount | Terminal | 10-year PV | Terminal PV | Balance-sheet adjustment | Fair market cap | Fair value/share | Margin of safety | Terminal share |
|---|---|---|---|---|---|---|---|---|---|---|
Bear | -2.0% / 1.3% | 11.0% | 2.0% | $1.16B | $0.802B | N/A (treated as $0) | $1.96B | $19.2 | -130.9% | 41.0% |
Base | 4.0% / 3.0% | 9.0% | 3.0% | $1.6B | $2.13B | N/A (treated as $0) | $3.73B | $36.6 | -21.2% | 57.1% |
Bull | 10.0% / 5.0% | 8.5% | 3.5% | $2.1B | $3.92B | N/A (treated as $0) | $6.01B | $59 | 24.8% | 65.1% |
In the reverse-DCF, holding the 9% discount rate and 3% terminal growth fixed, and solving only for one constant growth rate rather than using the base-case growth path, the current market capitalization implies roughly 6.1% annual free cash flow growth for ten years. This is a sensitivity framework, not a price target: the terminal-value share shows how strongly each result depends on assumptions beyond the explicit forecast. Negative margin of safety means the current market capitalization exceeds the scenario value.
Five Value-Investing Lenses
Benjamin Graham Lens
The Graham floor asks whether the market price offers downside protection relative to a conservative valuation of normalized earning power. The base-case scenario's implied per-share value is below the dated market price, and the bear-case value is well below it; the market is not paying for a margin of safety on Graham's terms. Balance-sheet liquidity is thin at $6.5 million of cash against $253.0 million of revolver borrowings and $450.0 million of net industrial revenue bonds at the Arkansas facility, with covenant headroom disclosed but no balance-sheet cushion to absorb a working-capital shock. Graham would likely classify the equity at $44.37 as a speculation rather than an investment until price and earnings normalize.
Benjamin Franklin Lens
Franklin's modern application is thrift, compounding and avoidance of needless spending. Trex's operating model uses recycled materials as feedstock, which is a discipline of thrift at the input layer, and the company has been steadily buying back its own shares at an average price that, depending on the repurchase-month mix, looks modest relative to the current quote. The question is whether continued repurchase at the current price is consistent with Franklin's opportunity-cost discipline: investing at full price into a single-name equity with covenant-limited leverage is the opposite of compounding from a position of strength. Until price discipline is restored, the buyback simply transfers capital from the balance sheet to selling shareholders rather than compounding it.
Warren Buffett Lens
Buffett's lens focuses on owner economics, moat and capital allocation. The accounting free-cash-flow proxy of $208.1 million is the starting point for an owner-earnings approximation that we have not separately adjusted for stock-based compensation given its small size, and that proxy supports a market multiple in the low-20s at the dated price. The moat evidence is brand, distribution and code listings, but the customer concentration in two national home centers is a moat-adjacent risk that Buffett would ask about. Capital allocation has been heavy on repurchase and Arkansas capacity; both are defensible, but a moat-thin cash-conversion profile at this share price does not match Buffett's owner-earnings hurdle.
Charlie Munger Lens
Munger would invert the thesis: the most likely wrong assumption is that gross margin will revert to 40.7% without further pricing discipline, because the Q2 2026 cost structure showed real input-cost pressure that has not yet been offset. Munger would also flag the channel concentration risk, the asset write-down at the Virginia facility, and the leverage implicit in the Little Rock industrial revenue bond structure, all of which raise the cost of being wrong. Opportunity cost is the alternative of waiting for a price closer to the base scenario before committing capital; bias risk is that a respected brand narrative can substitute for the cash-flow analysis, and the lens insists that the two be kept separate.
Li Lu Lens
Li Lu's circle of competence requires an understandable business model, durable competitive advantage, honest management and protection against permanent loss. Trex fits the first three reasonably well: a single-segment branded manufacturer with disclosed governance and a long-tenured category leadership position. Permanent-loss risk is the harder question: a residential construction downturn combined with channel inventory build and continued input-cost pressure could compress free cash flow for multiple years. The dated price does not protect against that scenario, so the Li Lu lens would keep the position sized small or wait for a clearer margin of safety.
Risks, Disconfirming Evidence, and What Would Prove This Thesis Wrong
The first observable thesis breaker is a sustained gross margin below the 39.1% six-month level, which would imply the input-cost pressure is structural rather than transitory and would invalidate any reversion thesis. The second is a working-capital reversal where accounts receivable does not collect in line with seasonal patterns, which would consume operating cash flow and force management to slow the buyback program. The third is any covenant pressure under the new credit agreement, where the company has covenant headroom today but would face limits if EBITDA falls materially. The most likely wrong assumption is that the 7.8% revenue growth observed in Q2 2026 will continue at the same pace; if housing turnover or repair-and-remodel spending weakens, that growth slows.
Disconfirming evidence already in the filings includes the $4.7 million Virginia write-down, the 158-basis-point six-month gross-margin compression, and the increase in revolver borrowings from $133.5 million to $253.0 million while buying back $153.6 million of stock. Each of these is a small data point on its own, but together they describe a company using leverage to reduce share count while the underlying operating margin drifts lower. We do not have peer pricing or share data to triangulate the implied franchise quality, so the disconfirming evidence is filed-fact only.
Investment Conclusion
The franchise has real brand, distribution and manufacturing assets, and the 2026 first-half cash generation was positive on both an accounting and a working-capital-adjusted basis. The dated market capitalization, however, sits more than 20% above the base-scenario equity value derived from the available free-cash-flow inputs, and the most recent quarterly evidence does not yet demonstrate the operating normalization that the market price implies. We therefore characterize Trex as Overvalued at $44.37 on October 15, 2026, while acknowledging that the bull-scenario outcome would justify a price above the current quote. The investor takeaway is to watch for evidence of gross-margin recovery, working-capital normalization, and a price closer to the base-scenario equity bridge before committing fresh capital.
This article is for educational and informational purposes only and does not constitute investment advice or an offer to buy or sell any security. All numerical evidence is drawn from publicly filed SEC documents and the available market snapshot; conclusions reflect author interpretation and may change as new information becomes available.
PLACES IN THIS STORY
Explore the destinations behind this report
United States
Little Rock
Browse travel guides, places to stay, attractions and local food in Little Rock.
Explore Little Rock →Little Rock Travel Guide: Planning Tips, Costs and Things to DoShare this article