Catch up on the essentials
- The strongest immediate industry signal is MinRes’s ability to expand throughput and physical sales at scale.
- MinRes reported 103 million tonnes of mining-services production for the three months ended September 30, 2026, up 10% from the June quarter.
- Dredging is scheduled to resume in mid-November and finish by the end of Q2 FY27, with only minimal expected impact on volumes.
Selected from this article · 2026-10-23
Read on for the full pictureMineral Resources’ September-quarter results point to stronger operating scale rather than a broad-based improvement in lithium pricing: attributable lithium sales reached a record 170,000 dry metric tonnes of SC6 spodumene, while mining-services production also set a record, and the company maintained FY27 guidance across its divisions.
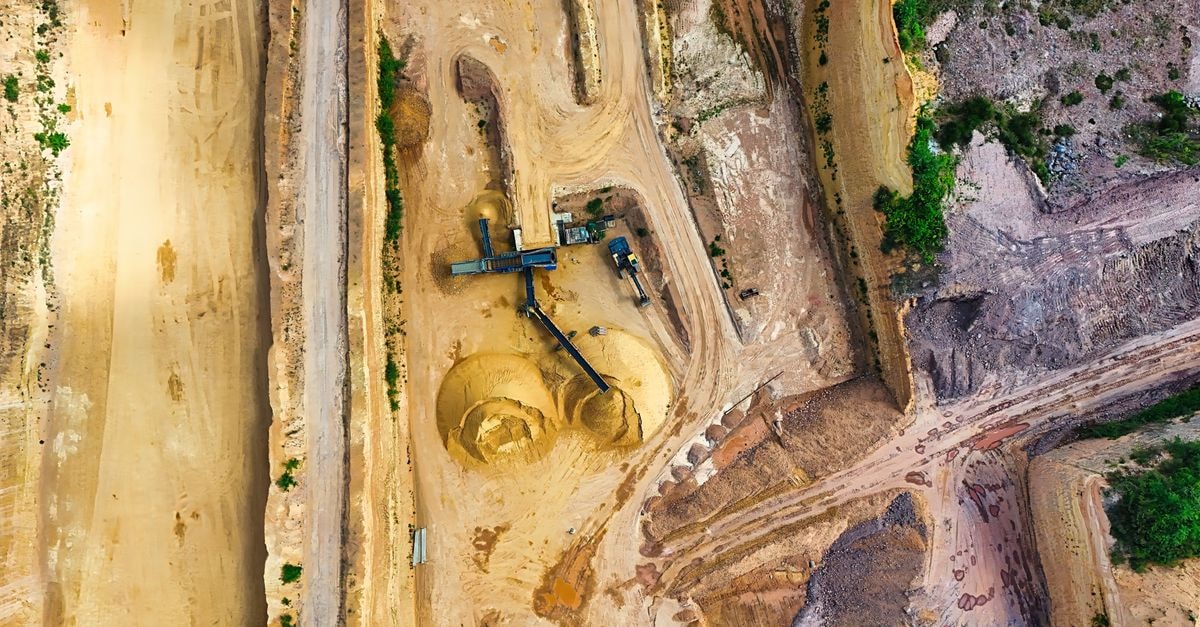
The strongest immediate industry signal is MinRes’s ability to expand throughput and physical sales at scale. The quarterly report shows operating momentum across mining services, iron ore and lithium, but weaker lithium spot-market conditions and cost pressure from rising diesel prices mean the volumes do not by themselves establish stronger margins or cash generation.
Record volumes expand MinRes operating scale
MinRes reported 103 million tonnes of mining-services production for the three months ended September 30, 2026, up 10% from the June quarter. The company attributed the increase to the ramp-ups of Bald Hill and Pilbara Hub and increased stripping at Mt Marion. It also commenced one new external ore-sorting contract, renewed two external crushing contracts and completed two contracts during the quarter.
Attributable lithium sales rose 8% quarter on quarter to 170,000 dmt of SC6 spodumene. The combination of higher lithium sales and record mining-services throughput indicates that MinRes entered FY27 with greater operating momentum. It does not, however, establish that lithium unit profitability improved: reported commentary said achieved lithium prices fell because spot markets weakened.
The company maintained its FY27 production and cost guidance across all divisions. That balance matters because MinRes appears to be adding volume while maintaining its operating guidance, although its outlook still depends on fuel costs, project execution and market pricing.
Lower prices limit the lithium signal
The record 170,000 dmt of attributable lithium sales shows that MinRes moved more concentrate during the quarter. The accompanying decline in achieved prices, attributed to weaker spot markets, means the volume increase should not be treated as equivalent growth in revenue or earnings.
This distinction is important for lithium suppliers and contractors: higher mine throughput can support demand for processing, transport and maintenance activity, but the available reporting does not identify specific equipment purchases or confirm that stronger physical output generated better margins. The company’s lithium performance therefore offers a positive operating signal without establishing a pricing recovery.
Mt Marion’s lithium flotation plant remained under construction, while the POSCO Holdings lithium transaction was still being prepared for finalization in the first half of FY27 and remained subject to outstanding conditions. Neither item should be treated as completed.
Services growth creates a broader demand mechanism
The mining-services result is the clearest near-term transmission mechanism for industrial demand. Record production reflected ramp-ups at Bald Hill and Pilbara Hub, increased stripping at Mt Marion and movement in the external-contract book. Those activities support the need for crushing, ore sorting, maintenance and haulage capacity, but the report does not identify incremental machinery orders or contract values for those categories.
Onslow Iron also recorded a 9.2 million wet metric tonnes of shipments on a 100% basis, including a September export month of 3.49 million wmt. The seventh transshipper was commissioned in August. Dredging is scheduled to resume in mid-November and finish by the end of Q2 FY27, with only minimal expected impact on volumes. These developments reinforce MinRes’s operating scale, although they are separate from the lithium sales signal.
Attributable iron-ore shipments across Onslow Iron and Pilbara Hub totaled 7.9 million wmt. The average realized iron-ore price was US$83 per dry metric tonne, down 5% from the June quarter. That decline illustrates why MinRes’s broader operating momentum should not be equated with uniformly stronger commodity economics.
Balance-sheet progress supports execution
MinRes reduced net debt by approximately A$200 million to about A$4.1 billion and increased liquidity by approximately A$100 million to A$2.5 billion. The company’s official report states approximately A$300 million of capital expenditure and payment of the FY26 dividend of approximately A$200 million; a secondary report gave different figures of A$310 million and A$160 million. Its liquidity comprised A$1.7 billion in cash and a fully undrawn A$800 million revolving credit facility.
Fitch upgraded the company’s credit rating to BB with a stable outlook from BB- with a stable outlook in September, citing capital-allocation discipline, significant deleveraging and expanding operations. The stronger balance sheet and credit standing improve MinRes’s capacity to fund existing projects, but they do not establish that additional supplier contracts have been awarded.
Procurement opportunities remain conditional
No procurement has been confirmed in the reviewed reporting. The strongest research watchlist comes from the disclosed growth in mining-services activity, where higher stripping, crushing, ore sorting and iron-ore logistics could create incremental demand for related equipment and services. The company’s capital projects and maintenance plans provide additional watchpoints, but the report does not disclose purchase orders, tenders or named suppliers for them.
Related industries and supply products
Industry / product or service | Evidence level | Event connection | Verification signal | Main risk |
|---|---|---|---|---|
Mining services — crushing and ore sorting | Inferred | Record 103Mt production and external-contract activity | New or renewed contracts, tenders or disclosed capex | Volumes may reflect existing assets rather than new purchases |
Mining services — stripping and haulage | Inferred | Increased stripping supported record throughput | Equipment commitments or contract awards | Fleet utilization and fuel costs may limit expansion |
Lithium processing — flotation and plant services | Research watchlist | Mt Marion flotation plant remains under construction | Construction milestones and equipment disclosures | Project timing and scope remain unconfirmed |
Port logistics — transshipment and maintenance | Research watchlist | Seventh transshipper entered service; dredging is scheduled | Maintenance, dredging and infrastructure awards | Timetable and volume effects may change |
Procurement opportunities
Product or service | Evidence level | Demand logic | Verification signal | Main risk |
|---|---|---|---|---|
Crushing, sorting and stripping support | Research watchlist | Record mining-services volumes reflect increased operating activity | Explicit tenders, contracts or capital commitments | No purchase is disclosed in the reviewed reporting |
Port transshipment and maintenance | Research watchlist | Seven-transshipper fleet and scheduled dredging indicate continuing port operations | Dredging or maintenance contract awards | Work may stay within existing operating plans |
Lithium flotation plant equipment | Research watchlist | Mt Marion plant construction could require processing equipment | Equipment selection, tender or installation disclosure | Procurement details and delivery timing are undisclosed |
Next checkpoint for volume and margins
The next observable test is whether MinRes can sustain the higher operating run rates while meeting its maintained FY27 guidance and avoiding further deterioration in lithium realized prices. Dredging resumption in mid-November and completion by the end of Q2 FY27 provide a near-term logistics checkpoint, while finalization of the POSCO Holdings lithium transaction in the first half of FY27 remains conditional. The reviewed excerpts do not disclose lithium production for the quarter, realized lithium prices or specific procurement awards, so the available evidence supports a volume-led operating judgment rather than a claim of stronger lithium economics.
Share this article